Statistics
Estimating Pi (π) with Monte Carlo Simulation in Python
Learn how to estimate the value of π using Monte Carlo simulation in Python. A step-by-step guide with math, code, and visualization.
An independent research journal
Making sense of markets,
one idea at a time.
The latest post Research
Discover Signed Dual Attention: an approach to model both positive and negative relationships in deep learning
Read the post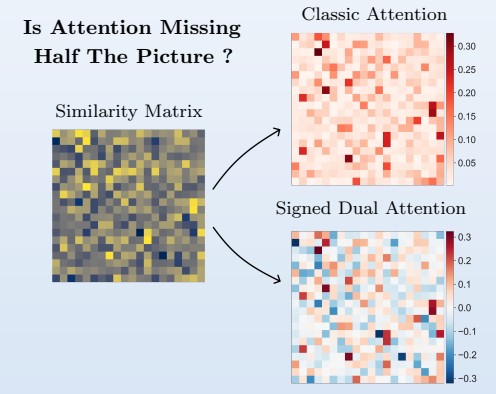
Statistics
Learn how to estimate the value of π using Monte Carlo simulation in Python. A step-by-step guide with math, code, and visualization.
Statistics
Learn how the risk-neutral measure mathematically transforms a random walk with drift into a martingale by removing its drift, with clear step-by-step explanations.
Quantitative Finance
Learn why factor models work in finance. Beneath their growing complexity in the number of factors lies a deeper unifying idea: factor models are, at their...
Quantitative Finance
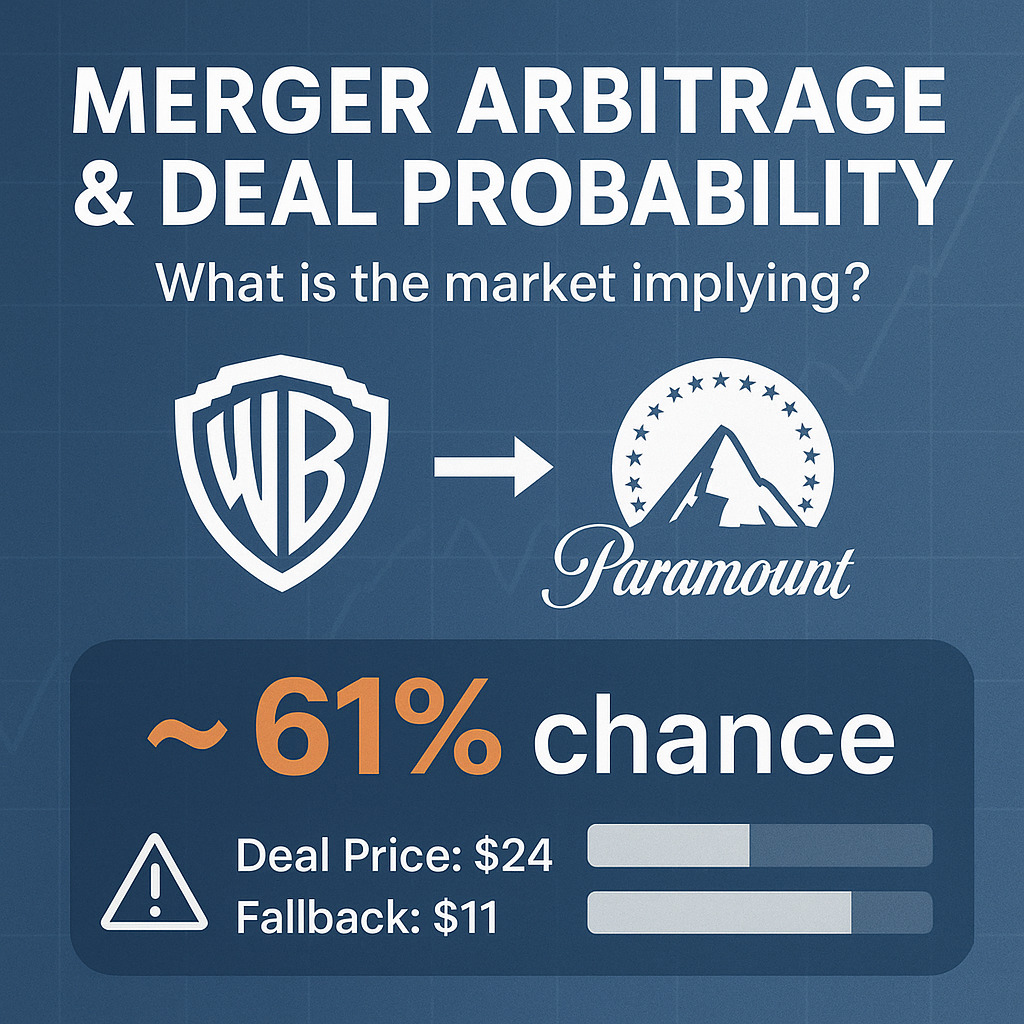
Learn how to analyze merger arbitrage opportunities using the Warner Bros Discovery and Paramount deal rumors. Break down market-implied probabilities, downside risk, and expected value like...
Python
Learn how to use Anaconda for your Python setup, allowing you to run .py files and jupiter notebooks.
Statistics
Learn the key differences between martingales and random walks in finance. Includes intuitive examples, asset pricing theory, and Python code.